Regarding the Euro

The biggest story of the last two decades has not been the opening up of China, rather it's been the creation of the Eurozone.
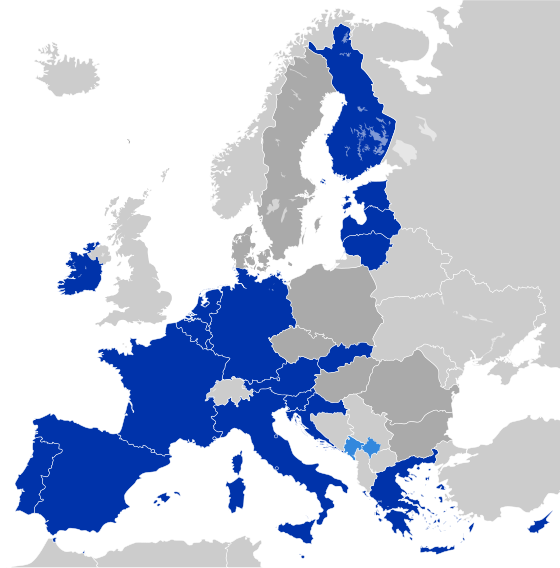
wiki media map of eurozone

First off, take the size of the combined economy of the Eurozone. In terms of GDP, it is larger than China, second only to that of the US (the European Union, which also includes the United Kingdom and much of Eastern Europe would be the world's largest economy, except that it quite doesn't function as one economy). 

Since I write about architecture, networks, and economy, the reason I am interested in the Eurozone is that it was an unprecedented construction of a single smooth space—to use Deleuzean terms—on a planetary scale. With the fall of the Iron Curtain in 1991, it seemed to confirm Deleuze's suggestion that the old regime of enclosures was giving way to a new world of modulations. Seemingly overnight, national currencies and border controls, the most familiar artifacts of modern nationhood, disappeared to get out of the way of the rapid circulation of capital and increased worker mobility. For Eastern Europe the delight in national independence at last swiftly faded, giving way to the rush to be subsumed into a larger union again, albeit voluntarily this time, without the Soviet Union's tanks and guns. 

What struck me during this period was the incredible openness of Europeans, both to each other and to those of us whose primary residence was abroad. As borders opened, so did minds. The development of the Internet went hand in hand with this opening up, allowing Europeans to go beyond the traditional boundaries of their national languages and literatures to share their ideas and learn from others at remarkable speeds. This is not to say that this wasn't going on everywhere, but it was particularly in evidence in Europe where the growth curve was very fast, a stark contrast to what was going on in the United States where thought often seemed stuck in the dark ages. For a time, Europe seemed to regain its status as the world's center of culture—as much as such a thing could exist—from the United States. Who would have thought, in 1991, that two of my books would be published by a press in Barcelona, that I would publish as much in European periodicals as in the United States, or that I would be teaching in Ireland part time? 

But as the August crisis—and the last three years teach us—that growth curve got ahead of itself and Europe now faces a grave economic crisis. The economies of European countries were at different places when they joined the Eurozone and there's no way that in a few years everyone could be at the same place as Germany. Where it seemed to happen, as in the last half of the Celtic Tiger, this was largely done on debt, a condition that has now been demonstrated as impossible to sustain. 

Now that the collapse of the Euro is being talked about as a real possibility, what sort of impact will this have on network culture? Is the Eurozone like the League of Nations, a great idea whose time has not yet come but will arrive, bigger and better soon? Or is it a historical anomaly? Even if globalization is a dominant economic force today, will a decade of economic stagnation couple with a collapsed eurozone lead to renewed calls for nationalism? Is the dialectic of smooth and striated space (remember, for Deleuze it was always a dialectic) about to shift again? 

These are some of the biggest questions for all of us this fall. 

Ivory Towers of Debt

Javier Arbona has a new piece up called “The Sorrows of Finance Capital,” in which he asks how it is that a university system in crisis can afford to build snazzy new buildings with vertiginously high budgets.

This is something that has bugged me a great deal lately. The credit crash has led to budget-tightening in universities, but the college building boom just keeps going. Whether it’s at SFSU—which as Javier points out, can’t afford an urban studies major anymore but can afford neomodernist digs—or at the University of Limerick, which during my at last visit a couple of weeks ago was sprouting more cranes than ever—it’s been a striking feature of the Great Recession.

As Javier points out, although the university brags that the building is funded by a $10 million gift, some $258 million (!) will have to come from construction funding. Now all this is—no surprise, alas—something that the press has chosen not to report on, and even seems to find hard to comprehend, as a series of Twitter exchanges between a newspaper critic and Javier on the above site demonstrates.

Universities have let a Wall Street mentality infect them. As a recent report by the Tellus Institute concludes, colleges and universities not only embraced risky investment strategies with their endowments, they continue to gamble with their money even after the 2008 crash. Tellus concludes that these universities “have been as much contributors to the financial crisis as they were victims of it.”

Part of the problem is that, as Karen Ho points out in Liquidated: An Ethnography of Wall Street, investment banks operate on ever-smaller time horizons. Lasting value is scoffed at in favor of immediate profits that can drive annual bonuses. With university boards populated not by faculty and researchers but by “leaders” in business, universities look at their endowments not so much in terms of sustainability and social responsiblity but rather as investments from which to wring maximum profits.

No wonder, then that university presidents are enamored with flashy construction projects which are much easier to justify to boards than equitably-paid faculty or low tuition for students (indeed, both of these are at odds with the sort of mentality that Ho observes on Wall Street: employees are always disposable and any university that keeps tuition down must be failing to charge apporpriately for its services).* After a few years at a university, the building-enamored president moves on to bigger and better digs, leaving faculty to struggle to get grants to fill buildings that shouldn’t have been built in the first place.

As a byproduct, universities issue bonds and, so long as endownments keep flowing in, can service them. It’s a giant ponzi scheme with little of value for students and, as Harper’s described in a notorious graphic about the consequeneces of overbuilding in Brandeis (Brandeis has threatened a lawsuit and has accused Harper’s of slander and libel over this piece), can collapse precipitously during times of economic crisis. But while bonds were hot, Wall Street couldn’t have enough of them, so universities eagerly complied.

With regard to Javier’s exchange with the critic, there’s been a lot of chatter lately about the effect of the Internet on the field and I suppose that for whatever reason, I’m going to have to add to that chatter on Tuesday at “Critical Futures” an event at Storefront. In anticipation of that event, I’ll conclude by observing that when design critics are unable to confront kind of issues that Javier raised in his piece, then we should be asking just what merit the field has in the first place, unless its merely cheerleading for the next building boom.

* At one institution that I once worked at, the director told the staff one year that cost of living increases were not possible due to poor finances. After delivering the news to the board that he had held staff salaries down, the chairman—a local businessman—moved to raise the director’s salary.

Read more

On Ireland, Briefly

Today’s news from Ireland is grim. As my readers know, I have been teaching in Ireland for some years.

I’ve expected this day since I first set foot there in 2005.

Faced by the impending bankruptcy of its banks and the consequent destruction of its tottering financial system, the republic is seeking a bailout from the IMF and the European Union (more here). The result is that another European country winds up on the same road that developing nations did in the 1980s and decades of austerity are to come. But where the banana republics of old were undone by the ruling elite’s direct expropriation of funds for infrastructural schemes, the countries being forced into perpetual indebtedness now are suffering because of a more collective delusion. This time, instead of infrastructural schemes, it was the bourgeoisie’s faith that they had found a pot of gold that animated the mania, making them the most earnest cheerleaders of the same big banks that they have to bail out now, the same banks that have led the country to the brink of ruin.   

The Celtic Tiger, if it ever existed, was created by the returns on productivity that external investment in a well-located, but underdeveloped, English-speaking nation brought. By the early 2000s, however, the Celtic Tiger was over and a new boom began around absurdly valued real estate. Even today, real estate in many parts of Dublin goes for more than comparable real estate in Manhattan. Since the latter is unquestionably overvalued by at least double (on a simple rent to price basis… seriously what other value can we give it besides rent multiplied by a degree of froth?), the former is thoroughly ludicrous. So even though I had seriously thought about moving to Ireland after George W. Bush’s reelection in 2004, and I dearly love the country, the economist in me panicked when I began looking into the real estate situation and I stayed put.  

I repeatedly warned about the impending collapse of an economy based on froth upon froth. Now it’s finally happened and the price will have to be paid. Although Ireland would probably have done better to go it alone and refuse to bail out the banks, imposing heavy taxes on corporations and the mega-rich, they’ve decided to seek aid from the IMF. The "cure" will be akin to massive chemotherapy. It certainly won’t be pleasant.

Sadly, there’s little question that architects and architectural institutions as well played a role in this debacle. Schemes for housing millions of  new residents expected to come to the country in the coming decades were eagerly drawn up even when there was no industrial or economic basis for such a massive increase in population. Such projects schemes validated the boom. Why weren’t plans drawn up for controlled shrinkage during impending contraction or for how to utilize the massively overbuilt housing? Alas, the answer is simple: such thoughts didn’t fit with the mantra that the boom would never end. Ireland was different, I was told time and time again, and unlike the tired old United States, it had discovered the secret for perpetual growth. 

But such growth could only come from the fairy people and, as is their wont, they turned out to be a devious bunch, eager to lead the deluded, greedy, and overeager astray. 

Now it’s time for the hard planning and thinking that should have been done a half decade ago or earlier. It’s time to reconsider what architecture means in a shrinking economy and with a shrinking population that seems likely to lose 10% of its population within a decade. As always, I’m ready to help by offering my input on the rebuilding process.

I hope this time somebody will want to listen.